SNB interest rates and exchange rates: What the monthly data say
The National Bank's October statistics bundle different market measures. For monetary policy they are a measuring point, not a new forecast.
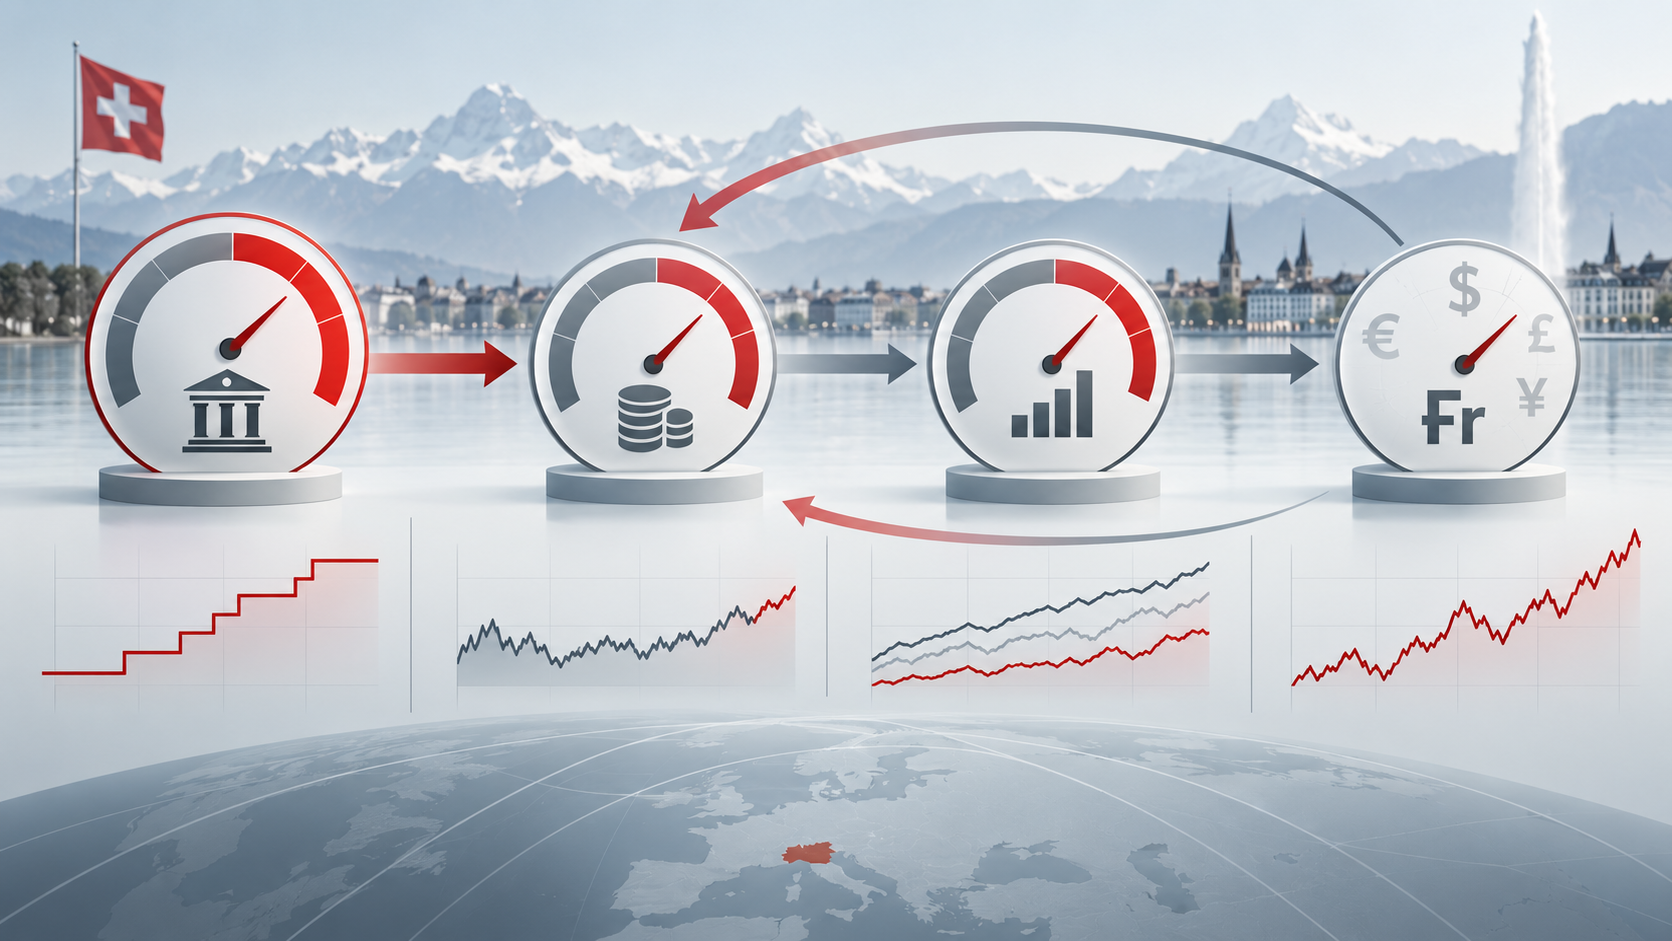
Anyone looking at the Swiss National Bank's (SNB) monthly data note finds interest rates, yields and exchange rates side by side. That is useful, but it can easily lead to wrong conclusions: the figures describe different parts of the financial system. A monthly sheet is neither a new monetary policy decision nor a forecast for the franc, interest rates or mortgages.
On 1 October 2026, the SNB reported its policy rate unchanged at 0.00 percent. The rate has applied since 20 June 2025. It is the National Bank's central monetary policy instrument. However, the policy rate does not directly set the price of every financing arrangement in everyday life. Banks, the capital market and expectations additionally influence the terms actually charged.
Three rates, three statements
At the end of September, SARON stood at minus 0.07 percent. It reflects the secured overnight transactions actually concluded in the Swiss franc money market. That it deviates from the policy rate is not a contradiction: it responds to liquidity in the money market and is calculated from transactions.
The yield on a ten-year Confederation bond was 0.639 percent on 1 October. It shows the return at which investors traded Swiss government paper over a long maturity. This yield embeds expectations about inflation, the economy and future interest rates, but also supply and demand for safe investments. It is therefore not a prediction by the SNB, but a market observation.
For households, the distinction matters. Fixed-rate mortgages are guided more by capital market yields than by the policy rate. Money market mortgages, by contrast, often follow a reference rate such as SARON. Anyone looking only at the policy rate therefore does not get a complete picture of their own financing costs.
Exchange rates are snapshots
For 1 October, the SNB published a euro rate of 0.9431 francs and a dollar rate of 0.8353 francs. For 100 Japanese yen the reference value was 0.5273 francs, and for the British pound 1.1036 francs. These figures serve statistics and calculation. They do not mean that the National Bank is targeting a particular rate.
The franc is traded continuously on the foreign exchange market. Exchange rates respond to international interest rates, economic data, risks and expectations. A single daily value therefore allows no robust statement about the competitiveness of export companies or about the holiday budget in the coming months.
A useful dataset, with clear limits
The SNB makes the series continuously available in its data portal. Their value lies in comparability over longer periods. Only when developments are observed over several months and linked with monetary policy decisions and economic data does a more meaningful picture emerge.
For 1 October, the sober reading remains: the policy rate was at zero, money market and capital market rates deviated from it, and the franc was traded at the published reference rates. Nothing more can be seriously derived from a monthly note.